

Last week, Kimi K3 just beat Claude Fable 5 on some FrontEnd Code Arena. Polymarket posted it as breaking news, and the internet did what it does: argued about benchmarks, methodology, whether Arena.ai scores mean anything. That argument misses the story.
Kimi K3 won’t hold the top spot long. Some American lab will reclaim it in a month, then lose it again. Model leaderboards flip constantly now — a 17-place jump in one release cycle, per Arena.ai’s own numbers. Chasing churn is a trap. The big story is in the economics that make releases like K3 possible at all. Hint it has something to do with structure and electricity!
Start with Kevin Walmsley’s numbers. Chinese AI models now process 98 trillion tokens a month against 53 trillion for US models. Chinese token demand more than doubled in a single month; American demand grew 43%.
DeepSeek’s latest model runs at 14 cents per million tokens against $5.00 for ChatGPT — a gap of roughly 35x.
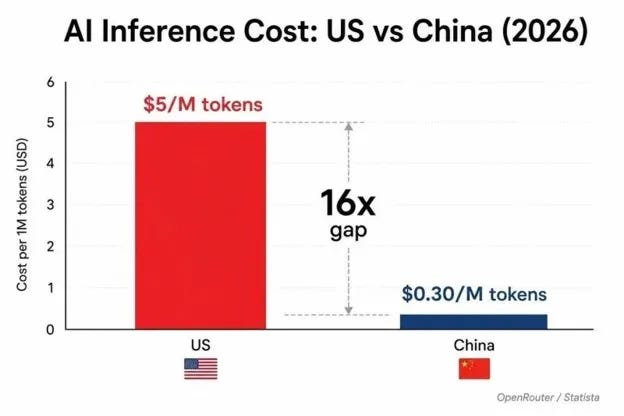
Real companies are switching on that math alone. Lindy moved 100% of its workload off Claude to DeepSeek and called the savings a survival issue. US commercial real estate firms are running lease reviews for pennies instead of dollars. Chinese models now handle up to 46% of US enterprise token volume.
None of that is about Chinese labs being smarter. It’s about them being radically cheaper to run, at scale, indefinitely. And cheap-to-run is not a research achievement — it’s an input-cost story.
That’s where StudioAlpha’s piece on Kimi K3, WAICO, and Xi’s Shanghai speech lands the harder point. Xi didn’t show up in Shanghai with a model demo. He showed up with an offer: training slots, cooperation centers, a new 29-country institution headquartered in Shanghai, and infrastructure for countries priced out of American frontier systems. That’s a bid to become the default AI supplier for most of the world, not just the top scorer on one leaderboard. Another example of China positioning itself to lead the electrotech revolution sweeping the globe.
Electric Feel
Both pieces are describing the same underlying asset from different angles. Walmsley is looking at the output — tokens sold at a tenth of the American price. StudioAlpha is looking at the geopolitical packaging — infrastructure diplomacy wrapped around cheap models. Neither piece names the input that makes both possible: electricity.
Training and running a frontier model is, at bottom, an energy bill. China’s installed power generation capacity hit 3.96 billion kilowatts by the end of March, up 15.5% year over year — roughly three times US installed capacity. Solar capacity alone grew 31% in a year; wind grew 22%. China is not matching the US watt for watt. It’s building a grid three times the size and still accelerating, while US and European demand growth stays flat by comparison. Don’t believe the hype. The hyperscalers are not building nor using nearly as much electricity as it seems.
Wall Street just confirmed it from the other side of the ledger. At least ten power and clean-tech companies went public in 2026 in the USA, raising $11.6 billion — a sector record, and more than software or biotech IPOs raised over the same stretch. Fervo, Forgent, Madison Air, Constellation: all pitching some version of the same thesis.
One investor tracking the wave put it plainly: you can ship chips from Taiwan and memory from Korea, but you cannot ship electricity — it gets generated next to the data center or not at all, which makes power the one layer of the AI stack that can’t be outsourced.
That’s not a bet on an existing edge. It’s capital chasing a shortfall: US data centers need 41 gigawatts today and a projected 77GW by 2030, nearly double, in four years. China isn’t racing to close that gap. It’s already sitting on it.
Put the two datasets side by side and the picture sharpens. American AI capex from five companies alone is forecast near $764 billion this year, headed past a trillion by 2027 — eight times China’s roughly $100 billion. But that American spending is mostly buying chips and data centers to squeeze more output from a grid that isn’t growing much. China’s spending, comparatively modest, sits on top of a power base that’s already three times larger and still compounding at double-digit rates. Cheap electricity doesn’t show up as AI capex on anyone’s spreadsheet, but it’s doing more of the actual work than the chip totals suggest.
Two caveats: American per-capita electricity use is still higher than China’s, and the US retains a real edge in advanced chips and frontier research funding — American firms pulled in roughly $286 billion in private AI investment in 2025 versus about $12 billion in China. Cheap power doesn’t hand China the smartest model. It hands China the cheapest model that’s good enough.
This is the part that outlasts any single model release. Export controls can slow China’s chip access. They can’t fast-track an American grid that takes a decade to permit a transmission line. Benchmark wins swap hands weekly — Kimi K3 today, something else in August. Electrification doesn’t swap hands. It compounds, quarter over quarter, and it’s the one input in this race that the loser can’t buy back with a bigger check. Sorry Elon but China is bigger than Texas…
So when Polymarket flags a Chinese model beating Claude Fable 5, the right reaction isn’t to relitigate the benchmark. It’s to notice that the model is downstream of a resource advantage the US isn’t currently positioned to close. Cheap tokens, aggressive global distribution, an AI diplomacy offer to 29 countries — all of it sits on the same foundation. Not smarter engineers, not better research. Cheap electricity, at scale, built faster than anyone else is building it.
Sources: Berno, “Climate got a new customer”; Hediger, “China’s Next Move in AI”; Walmesley, “We were wrong about DeepSeek. Now Chinese AI companies export trillions of AI tokens.”;
Great piece Danny - thanks